
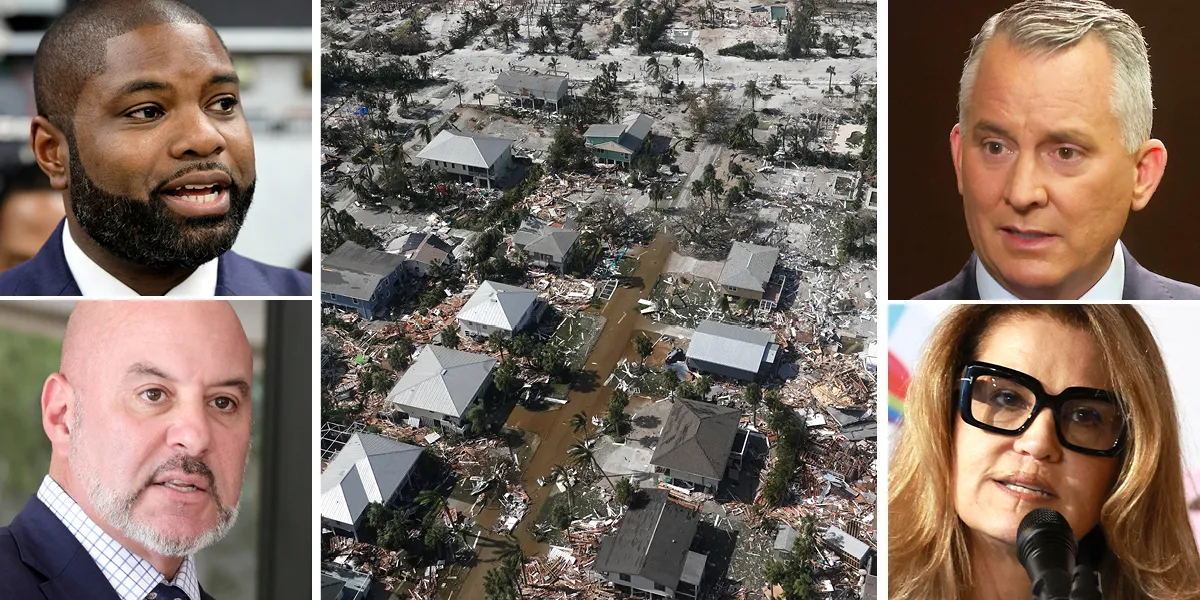
Property insurance has emerged as a leading issue in the runup to Florida’s November election.
Read more David Jolly, in Orlando, blasts Byron Donalds over support for data centers
As part of our Uncovered project exploring the impacts of the state’s 2022-23 insurance reforms, the Orlando Sentinel and South Florida Sun Sentinel submitted detailed questions to the candidates for governor and chief financial officer, the jobs that oversee insurance regulation, as well as to legislative leaders. Today, we are publishing their answers.
We asked what policyholders most want to know: How are you going to lower my insurance premiums? Can you get claims paid faster and fairer? And do you favor legislation requiring more transparency on insurers’ profits and practices?
The candidates outlined sharply different approaches to the issue, with distinctions particularly between Republicans who largely say the existing reforms are working but need refinement, and Democrats who say the state’s approach has failed and must be overhauled.
Of particular note are the contrasts at the top of the ticket between the candidates for governor, Republican Byron Donalds and Democrat David Jolly.
Donalds believes competition is already driving down rates, but says insurers must disclose more information about their business operations so Floridians understand what they’re buying.
Jolly is pushing to rethink the fundamentals of disaster protection for homeowners by shifting hurricane insurance to a state-controlled fund, with private companies handling more conventional coverage.
Here are the unedited responses to our questions:
Candidates for governor
Republican Byron Donalds, a former state legislator and U.S. congressman, and Democrat David Jolly, a former Republican U.S. congressman who switched parties in 2018:
What is your plan to lower property insurance premiums for Floridians?
Donalds: My Bring Down the Bill Plan builds on what’s working and goes after the costs still driving premiums up. First, we protect the 2022 and 2023 reforms that brought carriers back to Florida. Second, we increase competition by continuing to move policies out of Citizens and into the private market. Third, we use the Florida Hurricane Catastrophe Fund smarter: lower surcharges when reserves are strong, and let insurers pool reinsurance purchases to get better prices. Fourth, we supercharge home hardening, aiming mitigation grants at the projects that save the most, especially for homes built before 1992. Finally, we cut rebuilding costs through permitting reform, a review of building material mandates and reciprocal contractor licensing. Our goal is to bring costs down another 20 to 25 percent, without the $1,000 hurricane tax that David Jolly’s state takeover would impose.
Jolly: Under David Jolly’s proposal, instead of forcing every Florida family to pay a private insurer to take on that enormous hurricane risk, Florida creates one strong, state catastrophic fund. One fund, for the whole state, carrying hurricane and wind risk for Florida homes. That state catastrophic fund is built to a financially sound level and buys reinsurance for major storms. Coverage does not start until enough money is set aside in advance. There is no “hurricane tax.” The fund can be paid for by insurance companies paying the taxes they currently avoid, tourist taxes, and other sources, including an existing $12 billion hurricane fund that’s been funded by the Republican Legislature. Because private insurers no longer price hurricane risk into your policy, this plan can cut your insurance bill in half. The rest of your policy stays private, priced the way policies are in other states.
Does the insurance industry have too much power in Florida?
Donalds: No insurance company should have more power than the people paying the premiums. My job as governor is going to be to make sure Floridians have choices, carriers are held accountable, and families aren’t getting crushed by their insurance bills. For years, Florida didn’t have a healthy, competitive market. Carriers left the state, Citizens grew far beyond its intended role as the insurer of last resort, and homeowners were left with fewer options. When consumers have fewer choices, they have less leverage. That’s why I want more competition and more accountability. When companies have to compete for your business, they have to compete on price and service. And when they don’t live up to their obligations, the Office of Insurance Regulation needs to enforce the law and hold them accountable. What I don’t support is David Jolly’s plan to put hurricane risk into a state-run system and leave Florida taxpayers carrying the risk. I want to bring costs down by strengthening competition, increasing transparency, holding insurers accountable, and giving Floridians more choices — not fewer.
Jolly: Floridians are living with higher costs because our insurance system is fundamentally broken. It’s created and protected by politicians who’ve been captured by special interests, including the insurance industry, through our corrupt campaign finance system. We allow undercapitalized firms to come into Florida. We have a hurricane fund to bail them out when the big storm happens. We allow them to ship their profits out of state and keep their losses here. When the storms occur, they deny a large portion of the claims made by Floridians. They pay their CEOs $20 million in some cases. And, when it gets to be too much, they fold their company and they leave. That is the state of the homeowners insurance market here in Florida. When you’re the victim of a storm, the insurance companies too often aren’t there for you. And they’re protected by a broken set of laws in Tallahassee.
In 2022 and 2023, Florida enacted sweeping tort reform to curb lawsuits against insurance companies. What is your assessment of those changes, and would you support repealing or modifying any of those provisions?
Donalds: The reforms are working, and I will not repeal them. Since they passed, 21 new insurance companies have entered Florida. Citizens, which peaked at 1.42 million policies in October 2023, has shrunk dramatically as private carriers take policies back. Dozens of insurers have filed for rate decreases, and this year Citizens cut its average rates for the first time since 2015. Repealing these reforms would undo that progress and send Florida back into crisis. My Bring Down the Bill Plan builds on them instead, including optional binding arbitration so homeowners and insurers can settle disputes faster and more cheaply than in court. Floridians are starting to see relief. My job is to keep that going and bring premiums down even further.
Jolly: David Jolly believes homeowners should have the power to petition and sue insurance companies. The hallmark of the reforms in 2022 and 2023, which Byron Donalds praises and wants to continue, is that it’s now harder for Floridians to sue their insurance companies. That’s no way to protect consumers in Florida, and it’s yet another example of how the insurance companies are protected by a broken system.
Should any pre-reform coverage limitations — such as limits on water or roof coverage and 1% matching limits — be rescinded?
Donalds: I do not support rescinding them across the board. Florida’s insurance market is finally recovering, and wiping out coverage options that regulators approved would put upward pressure on premiums just as rates are starting to come down. What I do support is transparency. Homeowners should understand any roof, water or matching limit before they buy a policy, not discover it after a storm. Every policy with one of these limits should explain it in plain language. The better long-term answer is stronger homes. My Bring Down the Bill Plan restructures mitigation grants around the projects that produce the biggest insurance savings, and roofs are the clearest example. A homeowner with a new, hardened roof is far less likely to face a costly claim in the first place.
Jolly: David Jolly’s model, moving to a state catastrophic fund that covers all the wind and storm perils for homes, would change the broken insurance system and make these limits no longer apply.
Should Florida impose tighter regulations on the ability of insurance companies to move money to their less-regulated affiliated sibling companies?
Donalds: Yes. Floridians deserve to know their premiums are paying for coverage, not being drained through inflated fees to affiliated companies. A state-commissioned review found that some insurers’ affiliate fees were not fair and reasonable. That’s unacceptable. Florida law already lets regulators examine managing general agents as if they were the insurer itself. As governor, I’ll make sure the Office of Insurance Regulation uses that power aggressively. I’ll also work with the Legislature to require insurers to prove affiliate payments are fair, give regulators authority to order refunds when they aren’t, and stop affiliates from forgiving fees to make an insurer look healthier than it is. Legitimate companies have nothing to fear. The goal is accountability for bad actors, not driving good carriers out of Florida.
Jolly: David Jolly has called for a cap on the profits that property insurance companies can move out of Florida—lowering costs across the state for homeowners and renters. It’s legal in Florida for property insurers to quietly send huge profits out of state while saying they’re losing money, refusing to pay claims, and jacking up rates. As governor, Jolly plans to limit how much profit property insurers can send to sister companies out-of-state. These schemes make living in Florida more expensive for everyone, whether they own or rent, and the politicians in Tallahassee let it happen. This is the system Byron Donalds says is on the right track. But Florida’s voters want change. Currently, Florida law only requires that insurers’ payments to out-of-state affiliates be “fair and reasonable.” Jolly will use executive powers to narrow that standard, capping the amount companies can send out of state, lowering costs for Floridians.
What changes should Florida make so that hurricane claims are processed faster and insurance companies do not fight legitimate claims?
Donalds: Florida’s reforms already put insurers on a much tighter clock. Since 2023, companies have had to acknowledge a claim within 7 days instead of 14, inspect damage within 30 days instead of 45, including for hurricane claims, and pay or deny within 60 days instead of 90. Late payments accrue interest. As governor, I’ll make sure those deadlines mean something. The Office of Insurance Regulation can examine an insurer’s claims conduct after a hurricane, and I’ll expect it to use that authority, with real penalties for companies that delay or deny legitimate claims. My Bring Down the Bill Plan also offers optional binding arbitration, so homeowners can resolve disputes without a long court fight. And the best claim is one that never has to be filed. That’s why I’m aiming for mitigation grants at the upgrades that deliver the biggest savings.
Jolly: The private market for hurricane insurance in Florida has failed. David Jolly’s model, moving to a state catastrophic fund that covers all the wind and storm perils for homes, would change the broken insurance system and completely overhaul how claims are processed and paid, with any partners held to new, higher levels of accountability.
Insurers frequently invoke trade secret designations to shield information about how they set premiums, handle claims, and shift profits. Do consumers have access to the information they need to make informed choices, and would you support limiting the use of trade secret exemptions?
Donalds: Floridians should be able to compare insurers on what matters most: price, financial strength and how a company treats its customers after a storm. Right now, too much of that information is hard to find. Florida law lets insurers label information they submit to regulators as a trade secret, which keeps it out of public view. Some of that protection is legitimate, and stripping all of it away would risk scaring off the new companies our market needs. But a trade secret label should never be used to hide how a company handles claims or how much it pays its own affiliates. I’d support requiring regulators to review every trade secret claim, and publishing clear, consumer-friendly data on each carrier’s complaints and claim payment times. Transparency builds trust, and trust builds a healthier market.
Jolly: Requiring more transparency from property insurance companies is something Byron Donalds and I agree on. We should work with the Legislature to determine which specific rules and requirements are expanded. But, remember that transparency by itself doesn’t save you money—it just shows you exactly how you’re getting ripped off. Florida needs real, substantial reform and big solutions for these big problems.
Candidates for chief financial officer
Republican Blaise Ingoglia, a former state senator who was appointed CFO by Gov. Ron DeSantis in July 2025, and Democrat Annette Taddeo, a former state senator.
What is your plan to lower property insurance premiums for Floridians?
Ingoglia: Don’t undo the only thing that’s lowering rates. Before our 2022-23 reforms, Florida had less than 10% of the nation’s insurance claims and nearly 80% of its insurance lawsuits. Lawsuit abuse was rampant and Floridians were paying for it in the form of higher premiums. Since then, more than 20 insurers have entered Florida, and in 2025, while rates nationally went up 5.5%, Florida’s went down. The state’s own actuarial analysis found that without these reforms, the average homeowner could be paying 72% more. My opponent has no clue about how to bring down insurance rates. She can’t even pay her own bills on time. My opponent wants to undo those reforms which means your insurance premiums would almost double. I won’t let that happen. I’ll keep going after every unnecessary cost and fining any insurer that doesn’t pay what it owes.
Taddeo: Florida homeowners pay the highest insurance premiums in the nation, more than $8,000 a year. I know that pressure because I have been paying Florida insurance premiums for more than 30 years, as a small business owner and a mother. Within my first 100 days as CFO, I will publish an Insurance Company Report Card grading every company by name: how fast it pays claims, how often it delays or denies, how much it raises rates, and how much of your premium it sends to its own affiliates. Better information drives greater competition. I will use my Cabinet vote and my seat on the Financial Services Commission to fight for lower rates and full transparency from companies that cry poor while hiding their profits. I will appoint Citizens board members who answer to policyholders. Florida needs a CFO who will look at the numbers and follow the money.
Read more Penda frustrated by timing of injury as Magic continue to evaluate Wagner
Does the insurance industry have too much power in Florida?
Ingoglia: The power that matters is the power Florida families have over their own wallets. For years, lawsuit abusers did. Floridians paid sky-high premiums to fund a lawsuit machine to enrich a select few. I voted to shut it down and give the power back to Floridians. When insurers don’t treat Floridians right, I make them pay. We issued record fines to 10 insurers that mishandled claims. As CFO, I sued an insurer that needlessly drove up premiums. I sued another insurer for shady business practices. I pushed legislation to force insurers to show Floridians where every premium dollar goes. Florida homeowners and policyholders are my priority. Not the insurance companies. Not the trial lawyers. If you shortchange a Florida family, you’ll pay, literally.
Taddeo: Yes. Florida families pay the highest premiums in the nation while insurers claim losses and their own affiliates profit. That is not a level playing field. I saw it firsthand during five years on the Senate Banking and Insurance Committee, where I fought the insurance company bailouts and fought for the state to fund a study of insurer affiliates. That report was kept hidden for four years. When your newspapers obtained it, the Florida Senate demanded you destroy it. Blaise Ingoglia, who was appointed to this office, took at least a quarter million dollars from the industry he oversees, then voted for a $3 billion tax handout to insurers. The answer is not to punish insurers. It is to enforce the rules fairly and let regulators see what is happening inside these companies. The CFO should be a watchdog for consumers, not a rubber stamp for the industry.
In 2022 and 2023, Florida enacted sweeping tort reform to curb lawsuits against insurance companies. What is your assessment of those changes, and would you support repealing or modifying any of those provisions?
Ingoglia: They worked and the data is undeniable. Before the reforms, a few loose shingles on a roof turned into a lucrative business model for unscrupulous lawsuit abusers and every Floridian paid for it. We ended that. Since the reforms, lawsuit abuse has fallen sharply, insurers are coming back and creating competition that drives down rates. Unlike my opponent, I won’t repeal them and I won’t let anyone “modify” them into the same lawsuit mill under a new name. According to an actuarial analysis by the Office of Insurance Regulation, if you repeal the reforms, premiums would be 72% higher on average. My opponent may want higher premiums, but Floridians don’t. Here’s how I protect homeowners instead: when a carrier slows down a legitimate claim, we fine them. When they do something shady, we sue them.
Taddeo: Insurers asked for these changes and said they would bring rates down. They got the reforms. Florida homeowners still pay the highest premiums in the nation. That promise has not been kept. I fought the insurance company bailouts in the Senate. My test for any reform is simple: did it lower costs for families, or only for insurers? Fraud and abusive litigation are real, and my department’s fraud investigators will go after them. But a homeowner whose valid claim is lowballed or denied now has far less leverage to fight back. I support restoring a fair balance. When an insurer wrongfully denies or underpays a legitimate claim, the homeowner should not have to absorb the cost of making it right. I will use the bully pulpit to fight for that change in the Legislature, and my report card will show which companies pay and which stall.
Should any pre-reform coverage limitations, such as limits on water or roof coverage and 1% matching limits, be rescinded?
Ingoglia: This question mixes up two different things. The 1% matching limits and water damage limits were never part of the 2022-23 reforms, and they aren’t required by law. Insurers filed them, regulators approved them, and if a homeowner wants broader coverage, it’s available. Here’s what I voted for on roofs: Insurers can offer a separate roof deductible, and a few damaged shingles on an older roof no longer automatically means a brand-new roof. Before that, a simple $1,000 repair turned into a $20,000 bill, and every policyholder paid the price. I stopped that. If you repeal it, you are inviting insurance premiums to rise sharply and make things even more unaffordable than they are now.
Taddeo: Yes, I would fight to revisit them. Families pay record premiums and get less coverage in return. No homeowner should discover after a storm that the roof, the water damage, or a matching repair was quietly limited. At a minimum, every limitation should be disclosed in plain language before a family buys or renews a policy. My report card will show which companies limit roof and water coverage, so families can compare before they buy. I will use the bully pulpit to fight for coverage that makes homeowners whole, especially for older homes and roofs, where these limits hit hardest. Changing these laws requires the Legislature. As CFO, I will make the case every session, backed by the consumer complaint records my own department keeps.
Should Florida impose tighter regulations on the ability of insurance companies to move money to their less-regulated affiliated sibling companies?
Ingoglia: Yes, and I’ve already acted on it. In 2025, as Chairman of the Senate Banking and Insurance Committee, I put Senate Bill 888 on the agenda and passed it out of my committee. It would have forced every insurer to publish a transparency rate report, including what goes into your premium, whether they use affiliates, how they use them and how much of your premium ends up with them. All of it would be on a public website for every Floridian to see. The bill didn’t pass, but I’m not done. Transparency comes first, and I’ll keep fighting until Floridians can see exactly where their money goes.
Taddeo: Yes. The state’s own report, kept hidden for four years, found that from 2017 to 2019 insurers claimed $432 million in losses while paying fees to affiliates that earned $1.3 billion in net income. At least 17 companies paid their affiliates more than they said they lost. I fought in the Senate for the state to fund that study. Four years later, Tallahassee is still trying to hide it. The Florida House voted 106 to 3 to give regulators more power over affiliate payments. The bill died in the Senate. As CFO, I will use the bully pulpit to fight for that reform: a clear definition of “fair and reasonable” and full affiliate disclosure. My report card will show each company’s affiliate share. This is not about taking sides against the insurance industry. It is about clear rules, and a regulator with the information to enforce them.
What changes should Florida make so that hurricane claims are processed faster and insurance companies do not fight legitimate claims?
Ingoglia: I enforce the deadlines and laws already on the books, and I go after what’s really slowing claims down. A claim doesn’t move while it’s waiting on an overbooked adjusting firm to show up. It doesn’t move while a public adjuster is chasing the loss and building a second estimate the insurer then has to re-inspect. I’m rooting those delays out. My department also runs a mediation program that helps to close claims fast, without the cost and delay of a lawsuit, and I’m getting the word out so every Floridian knows it’s there. Any insurer that sits on a legitimate hurricane claim will answer to me. Just ask the ten that already got fined.
Taddeo: Two years after Milton and Helene, families are still fighting to get their claims paid. Right now, when an insurer stalls, homeowners are on their own. As CFO, I will send storm strike teams from the Department of Financial Services into hit communities within 3 to 5 days of landfall, in person, helping families push stalled and lowballed claims. No new law required. I will turn the state’s insurance helpline into a unit with teeth. When a carrier lowballs or denies, my office will demand answers, escalate to investigators, and refer bad actors for enforcement. I will expand the state mediation program so families can fight a lowball offer without hiring a lawyer. After every storm, I will publish a report on how many claims my office helped move. My report card will show which companies pay quickly and which stall, by name.
Insurers frequently invoke trade secret designations to shield information about how they set premiums, handle claims, and shift profits. Do consumers have access to the information they need to make informed choices, and would you support limiting the use of trade secret exemptions?
Ingoglia: No, consumers don’t, and I’ve already fought to change that. Floridians should know exactly how an insurer justifies what it charges, so they can choose who they do business with. I passed a bill out of my committee that would have required it. With every rate filing, consumers should see what percentage of their premium goes where, including how much and why. As CFO, I run the consumer protection side of insurance regulation, and I take that seriously. If an insurer has nothing to hide, it has nothing to fear from transparency. Your premium isn’t a trade secret. It’s your money.
Taddeo: No. Floridians buy the most expensive insurance in the nation with the least information about where their money goes. The affiliate report proves it. Floridians paid for it, and it was kept hidden for four years. When your newspapers obtained it through a public records request, the Florida Senate demanded you destroy it. Regulators now call it flawed and outdated but will not say what is wrong with it. Yes, I support limiting trade secret exemptions. Genuinely proprietary information can stay confidential. But the rate filings, claims practices, and affiliate payments behind what families pay should be public. I will use the bully pulpit to fight for that change in the Legislature, and I will oppose every effort to hide reports the public paid for. Until then, my report card will put what I can publish in families’ hands within my first 100 days.
Legislative leaders
Sen. Jim Boyd, R-Bradenton, left, president-designate of the State Senate, and Sen. Tracie Davis, D-Jacksonville, the incoming Democratic leader of the State Senate.
Boyd chose to not answer the questions, but his campaign provided this statement:
Over the last five years, the Legislature has instituted major reforms to offer homeowners more choice and lower costs when it comes to property insurance. The changes have attracted new insurance companies to the state, increasing competition and stabilizing rates. The expansion of options for homeowners has enabled us to roll off more than 1 million policies from the state-run Citizens Property Insurance Corporation, reducing risk to Florida taxpayers. The auto insurance market has also seen significant improvement with many insurers decreasing rates, and some even issuing dividends or refunds to policy holders. Still, there’s no question that hard-working Florida families and seniors are stretching every dollar to cover the rising cost of essentials. We’ll pursue every opportunity that can offer more choices and lower rates to Floridians, allowing them to save more of their hard-earned dollars, while maintaining the integrity and reliability of the industry we’ve worked so hard to reform.
Davis provided the following answers:
What is your plan to lower property insurance premiums for Floridians?
Davis: Floridians deserve accountability and real relief they have earned when it comes to solving our property insurance crisis. I believe we should be implementing rate caps to stop policyholders from continuing to be gouged and an excess profits tax, modeled on our currently existing statute regarding auto insurance, so hardworking Floridians can protect what they’ve built and first-time homebuyers get their shot at the American Dream. We should also look at state-backed universal windstorm coverage, which would lower rates, spread out risk, and safeguard policyholders from predatory private insurance corporations while giving families and seniors the protection and peace of mind they’ve paid for.
Does the insurance industry have too much power in Florida?
Davis: It is clear that the focus from Republican leadership has been to prioritize the needs of the insurance industry over what’s best for the people we were elected to serve. The so-called “reforms” that were passed over the last few years were a laundry list of the industry’s demands that has made it more difficult for policyholders to be made whole after disaster strikes and we are now seeing almost 50% of claims being denied without payment as a result. Additionally, instead of providing real relief to hardworking Floridians, the legislature passed $3 billion in taxpayer-funded bailouts at a time when rates were still skyrocketing. These priorities need to change and we should be looking at ways to help people struggling to pay their premiums every month instead of doing the bidding of the insurance industry.
In 2022 and 2023, Florida enacted sweeping tort reform to curb lawsuits against insurance companies. What is your assessment of those changes, and would you support repealing or modifying any of those provisions?
Davis: As I mentioned previously, I do believe these “reforms” have been a disaster for policyholders in the state and I would absolutely support their repeal. We should be working to make it easier for Floridians to be made whole after what’s often one of the most traumatic experiences they will endure, but instead we rolled out the welcome mat for greedy insurance companies to deny legitimate claims. Those are backwards priorities and we should do what we can to reverse these policies before more damage is done.
Should any pre-reform coverage limitations — such as limits on water or roof coverage and 1% matching limits — be rescinded?
Davis: I believe these provisions are another example of stacking the deck in favor of insurance companies and I would support their repeal. These are often arbitrary limits on water or roof coverage and the 1% matching limit artificially limits what a policyholder can receive in order to complete their repairs.
Should Florida impose tighter regulations on the ability of insurance companies to move money to their less-regulated affiliated sibling companies?
Davis: Yes. The recently released report highlighting how these companies were claiming losses while passing their profits through their affiliates was infuriating. What made it even more egregious is that instead of getting this information out to Floridians, the state has tried to cover it up. We need more transparency in the process and limits on the amount of money that can be passed through these affiliate companies to ensure that insurers are not using false claims of large losses to justify unreasonable rate increases on policyholders.
What changes should Florida make so that hurricane claims are processed faster and insurance companies do not fight legitimate claims?
Davis: The first step would be reversing the “reforms” passed over the last few years that have made this process easier for insurance companies to deny or lowball legitimate claims. While outright denials are a serious issue, not enough is being done to stop insurance companies from offering far below what the claim should pay because they know there is not the same threat of litigation when the state has removed the ability of attorneys to be fairly compensated for their work. This limits the ability of policyholders to be made fully whole and preys on people in potentially desperate situations who may be willing to take the offer simply because they need what they can get to begin the recovery process.
Insurers frequently invoke trade secret designations to shield information about how they set premiums, handle claims, and shift profits. Do consumers have access to the information they need to make informed choices, and would you support limiting the use of trade secret exemptions?
Davis: Unfortunately, without the help of licensed insurance agents to aid them in the process, I do fear that many Floridians are not getting the full picture of how their rates are set or the actual profitability of companies who have claimed massive losses to justify large premium increases. Rolling back the use of trade secret exemptions would allow consumers to more closely examine their options when choosing a carrier. I support limiting their use in cases where the information does not pertain to internal business practices, but could allow for more informed choices for consumers. Doing what’s best for Floridians and providing them more transparency should be our priority, not helping insurance companies hide relevant information from consumers.
NOTE: State Rep. Sam Garrison (R-Fleming Island), incoming speaker of the House, and State Rep. Christine Hunschofsky (D-Parkland), incoming Democratic leader of the House, did not respond to multiple requests for answers.
Read more Monday morning SpaceX launch could serve up space jellyfish encore